
When Family Ties Cause Tax Trouble
When Family Ties Cause Tax Trouble
The IRS does not care how much you love your family. Hiring a relative, renting to them, or doing business with them can trigger audits and disallowed deductions if you get the rules wrong. Studies show that family-related transactions rank among the top red flags the IRS watches for in small business returns. What feels like a simple family arrangement can quietly become a costly tax mistake.
How Do Family Transactions Create Tax Problems?
Family business dealings sit under a microscope. The IRS expects you to treat relatives the same way you would treat a stranger in any business deal. When you do not, the tax code steps in.
Here are the most common situations that create trouble:
Paying a family member an unreasonable salary. You can deduct wages paid to a spouse or child only if the pay matches what you would give any other employee doing the same work.
Renting property to a relative below market rate. If you charge less than fair market rent, the IRS may reclassify it as personal use. Your deductions go away.
Selling assets to family at a loss. The IRS calls these "related party" transactions. Losses on sales between family members are not deductible under IRC Section 267.
Loans with no interest or below-market interest. The IRS imputes interest on family loans using Applicable Federal Rates. If you skip interest, you may owe gift tax.
The Related Party Rules You Cannot Ignore
The tax code defines "related parties" broadly. It goes beyond just your spouse and kids.
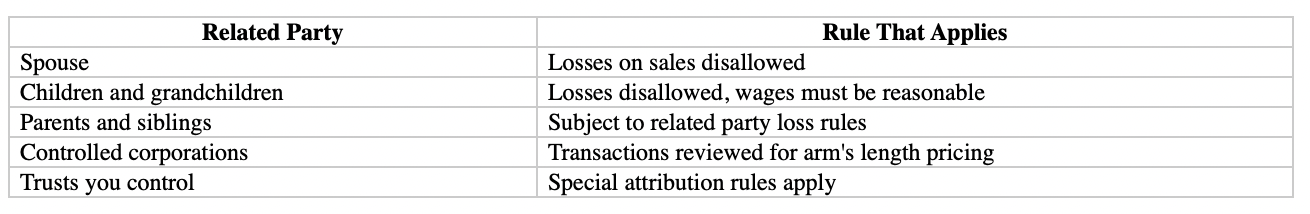
These rules exist to stop families from shifting income or manufacturing deductions that would not exist in a real business relationship.
What Happens When You Hire Your Child
Hiring your child is perfectly legal and can actually save taxes. You pay them a salary, they earn income at a lower tax rate, and you deduct it as a business expense.
The catch is simple. The work must be real and the pay must be fair.
A ten-year-old cannot reasonably earn $30,000 doing social media posts. If the IRS audits you, they will look at what the child actually did and what a non-family worker would earn for that same role. Anything above that is not deductible.
Children under 18 working in a sole proprietorship owned by their parent are exempt from FICA taxes. That is a real benefit worth using correctly.
Family Loans Done Wrong Become Gifts
Many families skip the paperwork on loans between relatives. No note. No interest. No repayment schedule. The IRS sees that and treats it as a gift.
If the loan exceeds $10,000, you must charge at least the Applicable Federal Rate. The IRS publishes these monthly. Fall below that rate and the IRS imputes the interest anyway. You owe tax on income you never collected.
Write a proper promissory note. Set a real repayment schedule. Charge the correct rate. That is what separates a legitimate loan from a taxable gift.
Protect Your Deductions Before It Is Too Late
Family transactions are not off-limits. They just need to be done right.
Document everything. Pay fair rates. Treat every family deal like a third party is watching, because at audit time, one is. Get your structure right from the start and your family arrangements can be both generous and tax-smart.